Selling into the UK: Guy Cliffe discusses customs, returns and duty reclaim

UKP Worldwide Director Guy Cliffe recently joined Cross-Border Magazine’s eCommerce Quick Fix podcast to explore what retailers need to know about selling into the UK, from preparing accurate customs data to managing returns and recovering duty.

The discussion looks at how Brexit changed UK eCommerce imports and why customs needs to be considered from the outset of an international shipping operation. Guy explains the importance of accurate HS codes, product values, weights and shipment manifests, and the problems that can arise when this information is incomplete or incorrect.

The episode also examines the UK’s £135 low-value threshold and BIRDS process as discussed at the time of recording, alongside the practical preparations businesses should make before sending their first parcels to the UK.

Looking beyond delivery costs

A central theme is the importance of assessing costs across the full customs lifecycle. Negotiating last-mile delivery rates is only part of the picture: retailers may also have opportunities to recover duty when imported goods are returned and re-exported.

During the recording, Guy reports that UKP Worldwide is reclaiming between £50,000 and £100,000 per week in duty for customers. He explains why connecting returns to the original import data is essential to supporting duty recovery.

Connecting imports, returns and exports

The conversation follows the practical journey of UK returns, including how goods are received, checked and processed before being exported back into Europe. It explores why customs information and physical returns handling need to work together.

Guy also discusses bonded warehouses, third-party logistics providers and transit models, as well as potential customs changes in 2028. Throughout the episode, he emphasises that the right approach depends on each retailer’s products, markets and operating model.

Watch the full episode below to hear Guy’s insights into managing UK imports, returns and duty reclaim.

To discuss how UKP Worldwide can support your business, contact info@ukpworldwide.com.

https://youtu.be/JB8YzaSmLi4


The EU’s €2 handling fee: why a small charge could make a big difference

Two euros may sound like a modest addition to an international order. For businesses selling lower-value products into the EU, however, the proposed handling fee raises a bigger question: how much will each basket cost to deliver once all the charges are accounted for?

The latest announcement brings more clarity to the EU’s customs changes. It also highlights why retailers should look beyond headline amounts when planning pricing, fulfilment and the customer experience.

What has been announced?

The European Commission has adopted a delegated regulation setting the Union handling fee at €2 per item for goods sold through distance sales to customers in the EU. The fee is intended to cover customs processing costs, including data checks, risk assessment, controls and supporting infrastructure. The entity responsible for the item’s other customs charges would also be responsible for the handling fee.

The measure remains subject to scrutiny by the European Parliament and Council. If neither objects, the regulation will enter into force on publication in the Official Journal and apply ten days later. Businesses should therefore avoid presenting 1 November as an unconditional, confirmed start date.

Why €2 and €3 are different charges

The handling fee is separate from the temporary €3 customs duty introduced on 1 July 2026 for qualifying low-value imports. Although the amounts are similar, their purposes differ. The €3 charge is a customs duty; the €2 fee is intended to recover the costs of customs supervision. The handling fee does not replace the duty.

For retailers, the commercial question is how these charges combine with import VAT and any applicable clearance or carrier charges—and who accounts for each amount. That makes it important to assess the complete cost of an order before making pricing decisions.

One parcel does not necessarily mean one fee

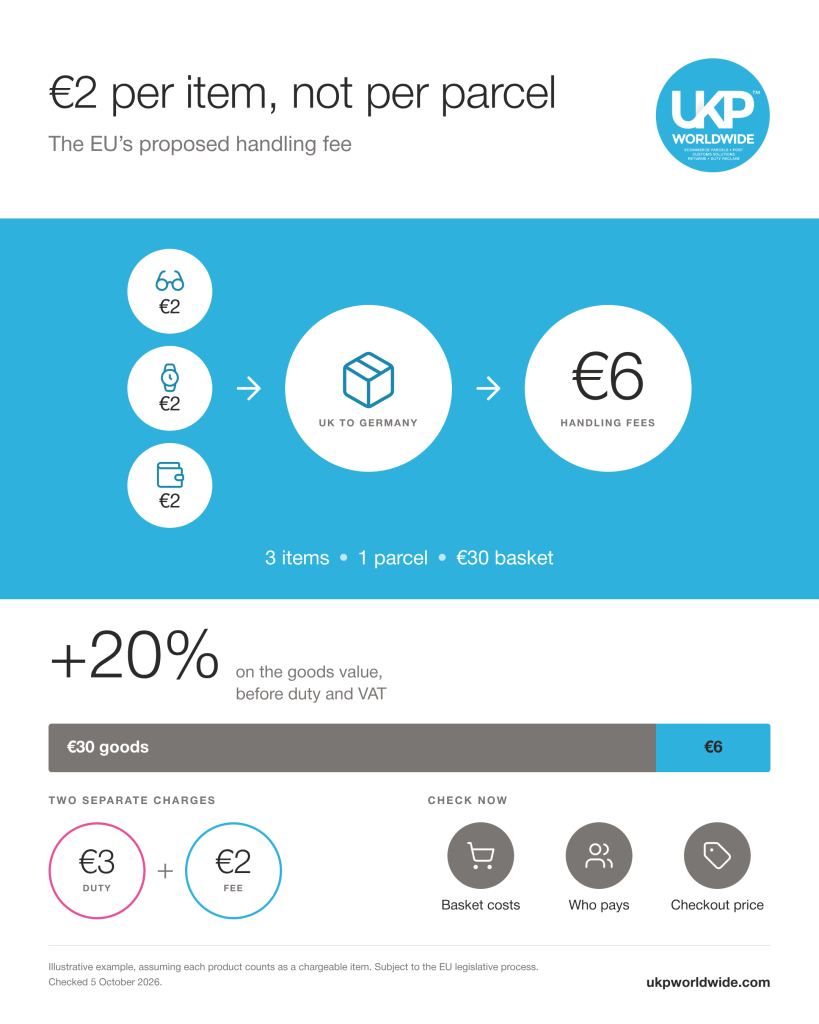
Imagine a UK accessories retailer sending an order to a customer in Germany. The customer buys three products worth €30 in total, all packed in one parcel.

For planning purposes, if each product counts as a separate chargeable item, the handling fee would add €6 to the order. That is equivalent to 20% of the goods’ value, before considering customs duty, VAT or other applicable charges.

This is an illustrative scenario, rather than a confirmed calculation for every three-product basket. Businesses will need to check the applicable definition of “item” and operational guidance before using it in live pricing. The €3 duty must also be calculated under its own rules; retailers should not assume both charges count items in the same way.

The example nevertheless demonstrates the commercial significance of those two words: “per item”. Combining products in one package may reduce transport costs, but it does not automatically reduce an item-based customs charge.

What should businesses do now?

While the legislative process continues, retailers can prepare by reviewing three practical areas:

  • Basket economics. Test the potential impact on typical EU orders, particularly baskets containing several lower-priced products. A fixed charge can take a larger share of the margin on a small purchase.
  • Responsibility for charges. Establish who will account for each amount across the selling platform, customs arrangements and delivery partners.
  • Customer pricing. Consider whether additional costs would be absorbed or reflected in prices, and how customers would see the total at checkout.

These decisions are closely connected. Absorbing a charge may protect conversion but reduce margin. Passing it on may preserve profitability while changing the customer’s perception of value. Understanding that trade-off starts with accurate order-level costs.

The bigger commercial lesson

The €2 announcement is a reminder that cross-border delivery costs are shaped by more than parcel weight and destination. The products inside the parcel, their customs treatment and the responsibilities of each party all matter.

For UK retailers, preparation means connecting customs requirements with pricing, basket composition and delivery promises.

At UKP Worldwide, we see that joined-up approach as essential to keeping EU trade commercially viable and giving customers a clear, predictable delivery experience.

Information checked on 5 October 2026. The handling fee’s application remains subject to the legislative process outlined above.

Sources


US tests new electronic customs entry for international mail

The way low-value goods enter the United States continues to change. On 22 September 2026, U.S. Customs and Border Protection (CBP) began testing a new electronic informal entry process for international mail through the Automated Commercial Environment (ACE). Known as Entry Type 13, or Informal Mail Entry, the voluntary test creates an electronic route for eligible international postal shipments valued at $2,500 or less.

It may sound like another technical customs update, but it reflects something much bigger: the continued move towards more structured customs declarations, better shipment-level data and clearer accountability for low-value goods entering the US.

Why has Entry Type 13 been introduced?

The test follows significant changes to the treatment of low-value imports into the United States, including the suspension of duty-free de minimis treatment for international mail.

CBP has introduced Entry Type 13 as an alternative electronic route for qualifying international mail. The test is intended to help CBP assess how an automated informal entry process can work in the postal environment and ultimately support the transition away from the current interim process.

Crucially, this is a test rather than a universal requirement. Participation is voluntary and CBP has not announced an end date. The test will continue until CBP concludes it through a further Federal Register announcement. However, the direction of travel is significant.
What information is required?

Entry Type 13 brings international mail further into the electronic customs environment. For participating shipments, information submitted electronically to CBP includes:

  • Importer of Record number
  • Merchandise description
  • Country of origin
  • Applicable 10-digit HTSUS classification
  • Value
  • Duty rate and total duty owed
  • Carrier name
  • Foreign postal operator tracking number
  • Arrival port

Quantity and weight are also required in certain circumstances, while additional information may be necessary where goods are subject to Partner Government Agency requirements or additional duties. An importation and entry bond is required, either as a single transaction bond or continuous bond.

Goods subject to anti-dumping or countervailing duties or quotas remain outside the Entry Type 13 informal process and require formal entry.

The bigger story is data

Perhaps the most interesting part of Entry Type 13 is not the new entry code itself, but what it says about the future of international eCommerce customs. A postal tracking number has traditionally been associated primarily with delivery and visibility. Under Entry Type 13, it also becomes part of the customs dataset.

Carriers participating in the test can provide the foreign postal tracking number within their manifest data. Where both the carrier and entry filer participate, CBP can use that number to match the arriving postal shipment with its corresponding customs entry. It is another example of the boundary between logistics data and customs data becoming increasingly blurred.

Product classification, origin, value, importer information and shipment identifiers all need to connect. For retailers, marketplaces, postal operators and logistics providers, that makes the quality of the information held before a parcel is dispatched increasingly important.

Who is responsible for the customs data?

There isn’t one party responsible for every piece of information. Data may originate with the retailer, manufacturer, marketplace or logistics provider, while the customs entry may be submitted by the owner or purchaser of the goods or an appointed customs broker. What matters is that responsibilities are clearly defined before goods are shipped.

Retailers and sellers need to ensure accurate product information, including descriptions, classification, origin and value, is available to the parties responsible for completing the customs process. The Importer of Record also has specific responsibilities, while brokers and logistics providers rely on the quality of the information they receive to complete declarations accurately.

Entry Type 13 therefore reinforces a wider point for cross-border eCommerce: customs compliance depends on accurate data being captured at source and passed correctly through the supply chain.

What should businesses take from the trial?

There is no suggestion that every qualifying international postal shipment must now use Entry Type 13. It is important not to present the trial as a finished nationwide operating model. But businesses shipping eCommerce goods into the United States should pay attention to what CBP is testing.

Across international trade, authorities are asking for more detailed information about individual products and shipments, often earlier in the journey. Low value no longer necessarily means low scrutiny. The practical lesson is therefore bigger than Entry Type 13 itself.

Retailers and logistics providers should understand the data they hold, where it originates and whether it is sufficiently detailed to support increasingly electronic customs processes. As customs systems become more data-driven, getting the parcel to the border is only part of the job. Getting the data there accurately may be just as important.

Sources

U.S. Customs and Border Protection / Federal Register: Test of the New Electronic Informal Entry Process for Mail, published 24 June 2026.

U.S. Customs and Border Protection Cargo Systems Messaging Service: Implementation of Entry Type 13 Test in ACE for U.S. Mail Processing, confirming deployment to the ACE production environment on 22 September 2026.