Winning the international customer: why cross-border growth depends on what happens after checkout

Selling internationally has never been easier. Delivering a consistently good international customer experience is a different matter.

Retailers can translate their websites, accept international payments and reach customers around the world through marketplaces and social media. However, making a product available in another country is only the beginning. What happens after the customer presses Buy can determine whether they complete their purchase, buy again or abandon the brand altogether.

According to the DHL 2026 E-Commerce Trends Report, 70% of shoppers now buy internationally, compared with 60% in 2025. Meanwhile, 45% make cross-border purchases more than once a month. The opportunity is clear. So is the challenge.

A global website does not guarantee a global experience

Retailers understandably invest heavily in attracting international customers. Digital advertising, translated content, local currencies and suitable payment methods can all help a business reach new markets. Yet the customer journey does not end when payment is accepted.

For an international order, it continues through product data, customs clearance, duty and tax handling, delivery, returns, refunds and, potentially, getting the product back into saleable stock.

Research shows that 67% of online shoppers have abandoned a basket because of the delivery options available. Seven in ten will not shop with a retailer if they do not trust its delivery and returns provider.

Logistics is no longer simply a back-office function. It forms part of the customer proposition and can directly influence conversion, loyalty and brand reputation.

Customers see one journey

A cross-border order may involve a retailer, marketplace, payment provider, customs agent and several carriers. Each has a different role, but the customer rarely sees those separate responsibilities. They see one order, from one retailer, with one promised experience.

If a parcel is delayed, the customer is unlikely to know whether the cause was incomplete customs data, an unexpected duty charge, a carrier problem or information missing from the marketplace. They simply know that their order has not arrived when expected.

This is why the international customer experience must be considered as one connected journey:

Checkout → landed cost → customs → delivery → returns → refund → resale

A smooth checkout followed by an unexpected customs charge is not a smooth experience. Fast international transport offers little benefit if inaccurate product data holds the parcel at the border. A convenient returns portal only solves part of the problem if the goods are then delayed in customs or remain disconnected from the retailer’s inventory system.

Customs has a commercial impact

Customs processes are often invisible to consumers when they work well. When they do not, the consequences can become very visible.

Incomplete product descriptions, incorrect commodity codes, inaccurate values or missing origin information can lead to delays, additional charges and customs interventions. Unclear duty and tax arrangements can leave customers facing costs they did not expect when placing their order. These may begin as data or compliance issues, but they quickly become customer-service problems.

Businesses therefore need to look beyond whether a customs declaration can simply be submitted. The quality of the information, how it moves between partners and how exceptions are managed can all affect the customer’s experience.

The same applies when a product is returned. A cross-border return does not end when the customer hands the parcel to a carrier. It still needs to move through the appropriate customs process, be matched against the original order and import, reach the correct facility, trigger a refund and, where possible, return to available stock.

Retailers may also need to identify whether import duty paid on qualifying returned goods can be reclaimed. If returns, customs, inventory and finance data sit in separate systems, these opportunities can easily be missed. The consequences include slower refunds, stock remaining unavailable for longer and unnecessary costs being retained within the business.
International growth needs the right infrastructure

More than three in ten eCommerce orders are now being sent internationally. Among businesses that do not currently sell across borders, 25% are prioritising cross-border delivery capabilities during the next 12 months.

As more retailers pursue international growth, the question is not simply where demand exists. It is whether the business can consistently deliver the experience customers expect once an order crosses a border.

Retailers should consider:

  • Are duties and taxes clear before the purchase is completed?
  • Is the product data detailed and accurate enough for customs clearance?
  • Can delays and exceptions be identified early?
  • Does tracking remain clear as responsibility passes between providers?
  • Are returns, refunds, customs records and inventory connected?
  • Can eligible duty on returned goods be identified and recovered?

These are not separate customs, delivery and returns questions. Together, they define the international customer experience.

At UKP Worldwide, we see customs as part of a much wider commercial journey. The information supplied at the point of sale can affect clearance. Clearance can affect delivery. Delivery and returns can affect refunds, inventory and customer loyalty.

Customers may never see the systems, customs data or partnerships behind an international order. They will notice whether it arrives on time, whether the final cost is what they expected and whether returning it is straightforward.

Winning the international customer is therefore about more than reaching them. It is about ensuring the experience promised at checkout survives the journey across the border.

Source

DHL: 2026 E-Commerce Trends Report

The research surveyed 29,000 online shoppers and 5,800 eCommerce businesses across 29 countries between December 2025 and February 2026.
UKP Worldwide at PARCEL Forum ’26

UKP Worldwide was proud to exhibit at PARCEL Forum ’26, held from 14 to 16 September at the Gaylord Palms Resort & Convention Center in Orlando, Florida.

Representing UKP Worldwide at Booth 340 were Guy Cliffe, Sales Director, and Sarah Brennan, Strategic Account & Development Manager. Across the event, they met with retailers, eCommerce brands, marketplaces, logistics providers and other industry partners from the United States and beyond.

PARCEL Forum brings together professionals from across the small-package fulfilment, shipping and logistics sector. For UKP Worldwide, it provided an important opportunity to hear directly from businesses about the challenges they are facing when moving goods internationally.

Many of the conversations focused on UK customs clearance, cross-border compliance, duties and taxes, returns management and the practical complexities of shipping parcels into the UK and Europe.

With international eCommerce continuing to evolve, events such as PARCEL Forum offer a valuable chance to exchange ideas, understand emerging priorities and build relationships with businesses throughout the global parcel industry.

Thank you to everyone who visited Guy and Sarah during the event. We look forward to continuing the conversations that began in Orlando.

Watch our short video below for a look back at UKP Worldwide’s time at PARCEL Forum ’26.

The low-value eCommerce reset: why governments around the world are rewriting the rules

For many years, low-value import thresholds helped cross-border eCommerce grow. Parcels below a set value could enter a market without customs duty, while simplified processes kept millions of relatively inexpensive shipments moving through the border.

These rules were designed for a very different retail environment. Low-value parcels once represented a small part of international trade. Today, they are central to the way consumers shop.

As volumes have grown, governments around the world have begun asking the same question: do rules created to manage occasional low-value imports still work when eCommerce generates millions of individual transactions every day? Increasingly, the answer appears to be no.

A global shift, not an isolated policy change

The approaches being taken are not identical, but the direction is increasingly consistent. In the UK, the Government has confirmed that the customs duty relief currently available on goods valued at £135 or less will be removed. A new customs arrangement is expected to take effect by October 2028, with further work required to determine how duty should be calculated, collected and reported.

The EU has moved more quickly. From 1 July 2026, it removed the customs duty exemption for goods valued at €150 or less and introduced a temporary €3 customs duty on low-value items. This is intended as an interim measure ahead of wider EU Customs Union reforms.

The United States has taken a different route, suspending duty-free de minimis treatment for commercial goods valued at $800 or less from all countries. The change followed an earlier suspension covering goods from China and Hong Kong.

Elsewhere, countries including Australia and New Zealand have already introduced models that require overseas sellers or marketplaces to collect tax on low-value goods at the point of sale. These are separate policy decisions, shaped by different domestic priorities. Taken together, however, they point to a wider reassessment of how low-value eCommerce should be managed.

Why are governments reaching similar conclusions?

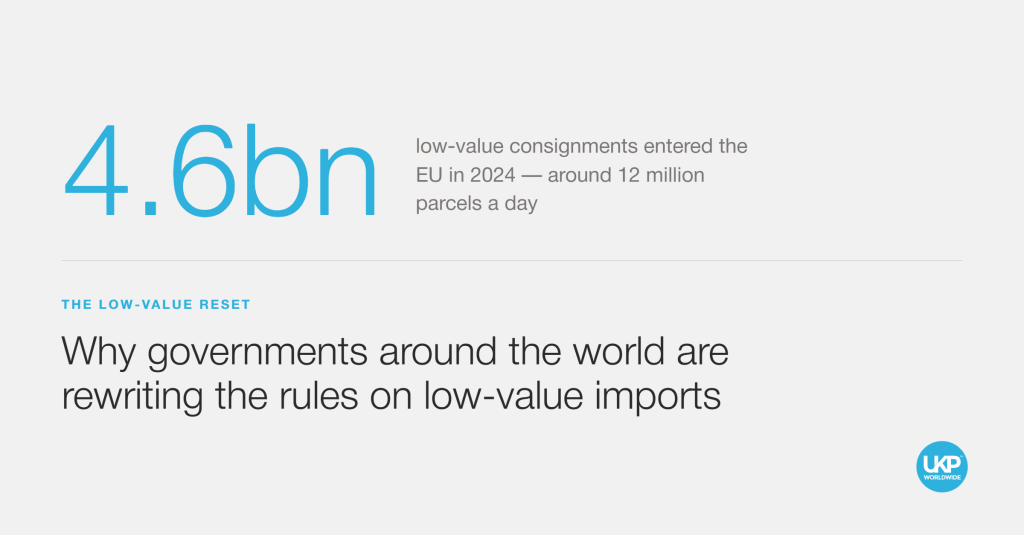
The clearest pressure is volume. The European Commission reported that approximately 4.6 billion low-value consignments entered the EU in 2024, equivalent to around 12 million parcels every day. This was twice the volume recorded in 2023 and three times the level seen in 2022.

At this scale, a customs exemption is no longer dealing with a marginal category of trade. It covers a significant and fast-growing share of consumer imports.

Revenue is part of the discussion, but it is not the only concern. Governments and domestic retailers have questioned whether exempting imported goods from duty creates an imbalance when businesses operating within the destination market must meet local tax, employment, product and environmental requirements.

Product safety has also become a prominent issue. High parcel volumes make it difficult for authorities to identify goods that are unsafe, counterfeit, incorrectly described or non-compliant with local standards. The European Commission has linked its eCommerce reforms directly to consumer protection and more effective enforcement.

There is also the question of customs capacity. Inspecting every parcel manually would be neither realistic nor proportionate. Simplified processes were created partly because the cost of assessing individual low-value transactions could outweigh the revenue collected.

What has changed is the technology. Advance electronic data, automated risk analysis and direct links between marketplaces, carriers and customs authorities are making it more practical to assess transactions before goods reach the border. Governments can increasingly identify higher-risk shipments without treating every low-value parcel in the same way.

The debate is therefore moving beyond whether low-value goods should be checked. It is becoming a question of how data and technology can make those checks possible at scale.

Reform brings its own risks

Removing or changing low-value exemptions does not automatically create a better system.

If new rules are introduced too quickly, consumers may face unexpected charges, overseas businesses may withdraw from certain markets and carriers may struggle to adapt their systems. The suspension of the US de minimis exemption demonstrated how significant the operational impact can be when postal operators, retailers and technology providers have limited time to prepare.

There is also a risk that complex processes could disproportionately affect smaller retailers. Large marketplaces are more likely to have the systems, data and resources needed to calculate duties across thousands of products. Smaller businesses may find the same requirements considerably harder to manage.

Successful reform will therefore depend on more than changing a threshold. Governments will need workable collection models, clear allocation of responsibilities, proportionate data requirements and enough implementation time for the supply chain to adapt.

Collecting charges at checkout, using marketplace-led models and transmitting accurate product data before dispatch are likely to become increasingly important. The objective should be to improve oversight without making legitimate cross-border trade unnecessarily difficult.

What this means for eCommerce businesses

The most important conclusion is not that low-value international trade is ending. Consumer demand for cross-border choice, convenience and competitive pricing remains strong.

What is changing is the assumption that a low-value parcel will require little customs consideration. Retailers, marketplaces and logistics partners should expect greater scrutiny of product descriptions, commodity codes, values, origin and safety information. Responsibility is also likely to move further upstream, with more duties and taxes calculated before dispatch rather than collected after a parcel reaches its destination.

Businesses should begin treating customs data as part of the customer transaction, not simply as information added later for shipping.

The global low-value reset is ultimately a consequence of eCommerce becoming too important to remain at the edges of customs policy. Governments are not all adopting the same solution, but they are responding to the same reality: systems designed for yesterday’s parcel volumes must now support one of the largest and fastest-moving areas of global trade.

For eCommerce businesses, the question is no longer whether the rules will change. It is whether their data, systems and supply chains will be ready when they do.

Sources


Peak season doesn’t end at delivery: why retailers need to plan for the January returns wave now

For many retailers, peak season planning focuses on getting orders out of the warehouse and delivered before Christmas. Yet delivery is not the end of the journey.

The purchases made during Black Friday and the weeks leading up to Christmas will create a second operational peak in January. Products will move back through customer service teams, carrier networks, customs, warehouses and finance systems before they can be refunded, restocked or resold.

This is not a minor part of the peak trading cycle. Research from Retail Economics and ZigZag forecast that UK non-food returns would reach £25.1 billion in 2025, equivalent to 19.5% of online orders. Clothing recorded an even higher average return rate of 23.6%.

The lesson for Peak 2026 is clear: a successful festive season cannot be measured by outbound sales and delivery performance alone. Retailers also need a plan for what comes back.

January exposes weaknesses that peak sales can hide

Returns can increase quickly once Christmas is over. In January 2026, more than £1.5 billion of unwanted Christmas purchases were expected to make their way back to UK retailers, with volumes forecast to rise by around 25% during the first full working week of the year. At quieter times, a fragmented returns process may appear manageable. During January, however, every gap becomes more visible.

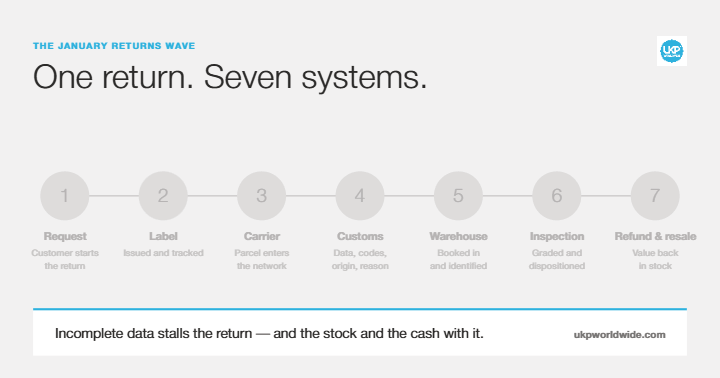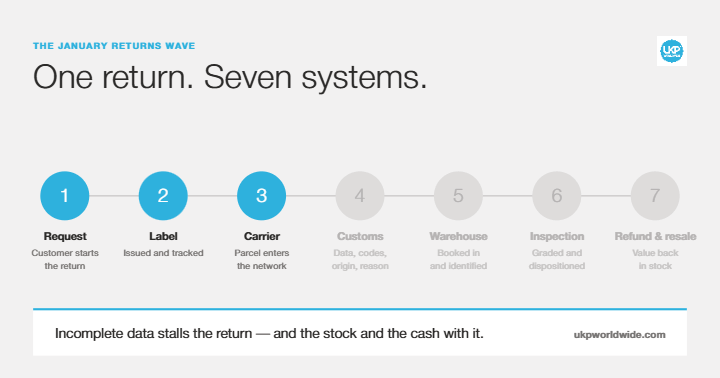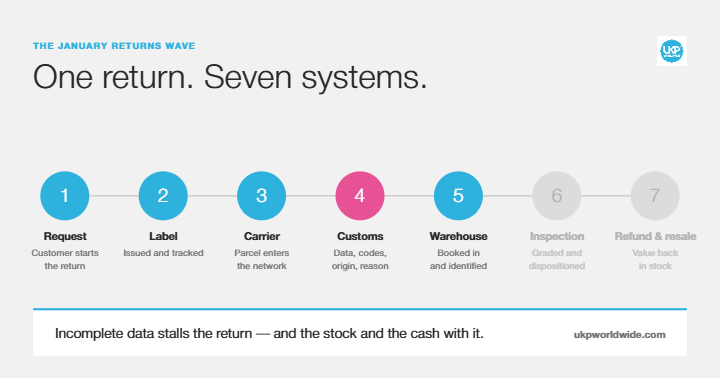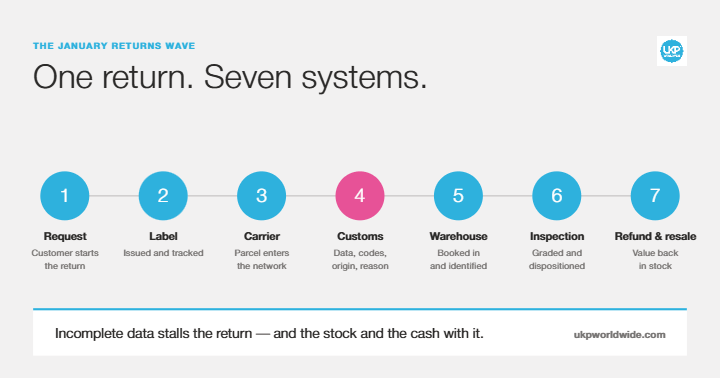
A returned item may need to pass through several separate systems before its journey is complete. The customer requests a return, a label is issued, the parcel enters the carrier network, customs information is submitted, the product arrives at a warehouse, its condition is assessed and the refund is approved.

If the information connecting these stages is incomplete, the return can stall. The warehouse may receive an item it cannot immediately identify. Customer service may not know whether the parcel has crossed the border. Finance teams may issue refunds without knowing what has happened to the stock. Customs evidence may be held separately from the original transaction. The individual delay may seem small, but multiplied across peak-season volumes, it can tie up significant amounts of stock and working capital.

Cross-border returns need more than a label

Domestic returns are largely a logistics exercise. International returns are also a customs exercise. The movement must be supported by accurate information, including the product description, value, commodity code, country of origin and the reason for return. It must also be possible to connect the returned item with the original order and the relevant customs records.

Poor data can result in parcels being delayed, incorrectly treated as new imports or charged duty and tax again. It can also make it more difficult to establish whether a business is entitled to customs relief or a repayment.

Depending on how goods originally moved and where they are being returned, different customs arrangements may apply. For example, Returned Goods Relief can allow eligible goods that were previously exported from the UK to be re-imported with relief from Customs Duty and import VAT. HMRC applies specific conditions, including requirements concerning the identity, condition and timing of the goods.

There may also be opportunities to reclaim import duty previously paid when imported products are subsequently returned and re-exported. Eligibility is not automatic. Businesses need the correct customs procedure and a reliable audit trail linking the import, customer return and subsequent export. If that evidence is not captured as part of the returns process, it can be difficult to rebuild several months later.

The real objective is to recover value quickly

Getting a returned parcel back into a warehouse is only one measure of success. The more important question is how quickly the business can recover value from it.

Seasonal products have a particularly short resale window. A winter coat received and inspected in early January may still be returned to stock and sold at a reasonable margin. The same coat sitting unidentified in a returns queue for several weeks may eventually require a heavier discount, be diverted to an outlet or miss the season completely.

This creates a direct link between returns processing and inventory planning. Retailers need clear rules for inspection, grading and disposition before January volumes arrive. Teams should know whether products can be:

  • returned immediately to available stock
  • cleaned, repaired or repackaged
  • resold through an alternative channel
  • consolidated and returned to their country of origin
  • recycled or responsibly disposed of

Visibility matters throughout this process. Customer service, warehouse, finance and customs teams should not be working from different versions of the same return.

Planning should begin before the first peak order

September may feel early to prepare for January, but the returns process needs to be tested before peak trading begins. Retailers should use the coming weeks to examine whether their returns policy, carriers, customs arrangements, warehouse capacity and internal systems can manage a sudden increase in volume. They should also confirm what data will be captured when a return is initiated and whether it can be matched with the original sale, import declaration and export movement.

Useful questions include:

  • Can every returned item be linked to its original order?
  • Is the product and customs data complete and consistent?
  • Who is responsible for the return declaration?
  • Can the business identify returns that may qualify for duty recovery?
  • How quickly can an inspected item become available for resale?
  • What happens when a parcel arrives without the expected data?
  • Do customer service teams have visibility of the complete return journey?

Peak season does not finish when the final Christmas order reaches the customer. It finishes when returned products have been identified, cleared, refunded and placed back into the most appropriate sales or recovery channel.

Retailers that treat January as part of peak planning will be better placed to protect margin, release working capital and recover more value from the stock that comes back.

Sources


CPTPP is now fully open to the UK. What does it mean for exporters?

The UK has reached an important milestone in its membership of the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP). Following Canada’s ratification of the UK’s accession, the agreement now applies between the UK and all 11 other members of the trading bloc.

From 1 September 2026, UK businesses can access CPTPP arrangements with Australia, Brunei, Canada, Chile, Japan, Malaysia, Mexico, New Zealand, Peru, Singapore and Vietnam.

The headline opportunity is significant. The UK Government says that more than 99% of current UK goods exports to CPTPP members will be eligible for zero tariffs over time. The agreement also covers services, investment and government procurement.

For exporters, however, access to a trade agreement and entitlement to its benefits are not the same thing.

Zero tariffs are not automatic

The 99% figure could easily be interpreted as a blanket removal of customs duty. In practice, preferential treatment depends on the product’s commodity code, the destination country’s tariff schedule, any tariff phase-out period and whether the goods meet the relevant rule of origin.

Goods do not acquire UK origin simply because they are sold by a UK business or dispatched from a UK warehouse. A product manufactured in a non-member country and resold from the UK may remain non-originating.

This is particularly relevant to eCommerce retailers sourcing internationally and selling the same goods into several markets. To claim CPTPP preference, a business may need to establish where a product was made, where its materials came from and whether any processing met the product-specific origin rule.

An incorrect preference claim can lead to duty being recovered after import, alongside additional administration and possible compliance concerns.

Cumulation could reshape sourcing decisions

One potentially valuable feature of CPTPP is cumulation. In broad terms, qualifying materials and production from participating CPTPP countries may be counted when determining whether a finished product is originating.

For a UK manufacturer with a supply chain spanning several CPTPP markets, this may make it easier to meet an origin rule. It could also influence future sourcing and production decisions.

Cumulation is not a shortcut, however. Each product must still meet its specific rule, which might require a change in tariff classification, a regional value calculation or a particular manufacturing process. Origin therefore needs to be assessed at product level and supported by reliable supplier and production records.

Canada brings an additional choice

Canada’s ratification is especially interesting because the Canada-UK Trade Continuity Agreement remains in force alongside CPTPP.

Businesses trading between the UK and Canada may therefore have more than one route to preferential treatment. The best option will not necessarily be the same for every product. The two agreements can have different origin rules, tariff treatments and documentary requirements.

Rather than automatically using the newest agreement, exporters should compare the available options. CPTPP may provide the better outcome in some cases, while the existing bilateral agreement may remain more suitable in others.

Tariff optimisation is not simply about finding a zero rate. It means identifying which rate is legally available, confirming that the goods qualify and holding evidence to support the claim.

The customs border remains

CPTPP is a free trade agreement, not a customs union or single market. Export and import formalities still apply when goods move between members.

Businesses must still consider classification, customs value, origin evidence, declarations, local taxes and product-specific controls. Responsibilities between the seller, buyer, carrier and customs representative must also be clear.

A lower tariff may improve the landed cost, but it does not remove the wider operational requirements of entering a new market. Delivery charges, tax arrangements, local regulation, returns and the customer experience remain part of the commercial calculation.

Turning access into an advantage

Businesses considering CPTPP markets should begin with a focused review of their products and supply chains. Key questions include:

  • What is the correct commodity code?
  • What are the standard and preferential tariff rates?
  • Which origin rule applies?
  • Can the business demonstrate how and where the goods were produced?
  • Is CPTPP the most appropriate agreement for the transaction?
  • Can the required evidence be produced if the claim is checked?

Some products may already enter at a zero standard rate, making preference unnecessary. For others, the saving could be meaningful but dependent on stronger supply-chain data.

Full access to CPTPP may support lower tariffs, more flexible sourcing and new export opportunities. But its value will be determined product by product and supply chain by supply chain. The businesses most likely to benefit will combine commercial ambition with accurate classification, a clear understanding of origin and reliable evidence.

The opportunity is real. Turning it into an advantage begins with understanding the detail.

Sources


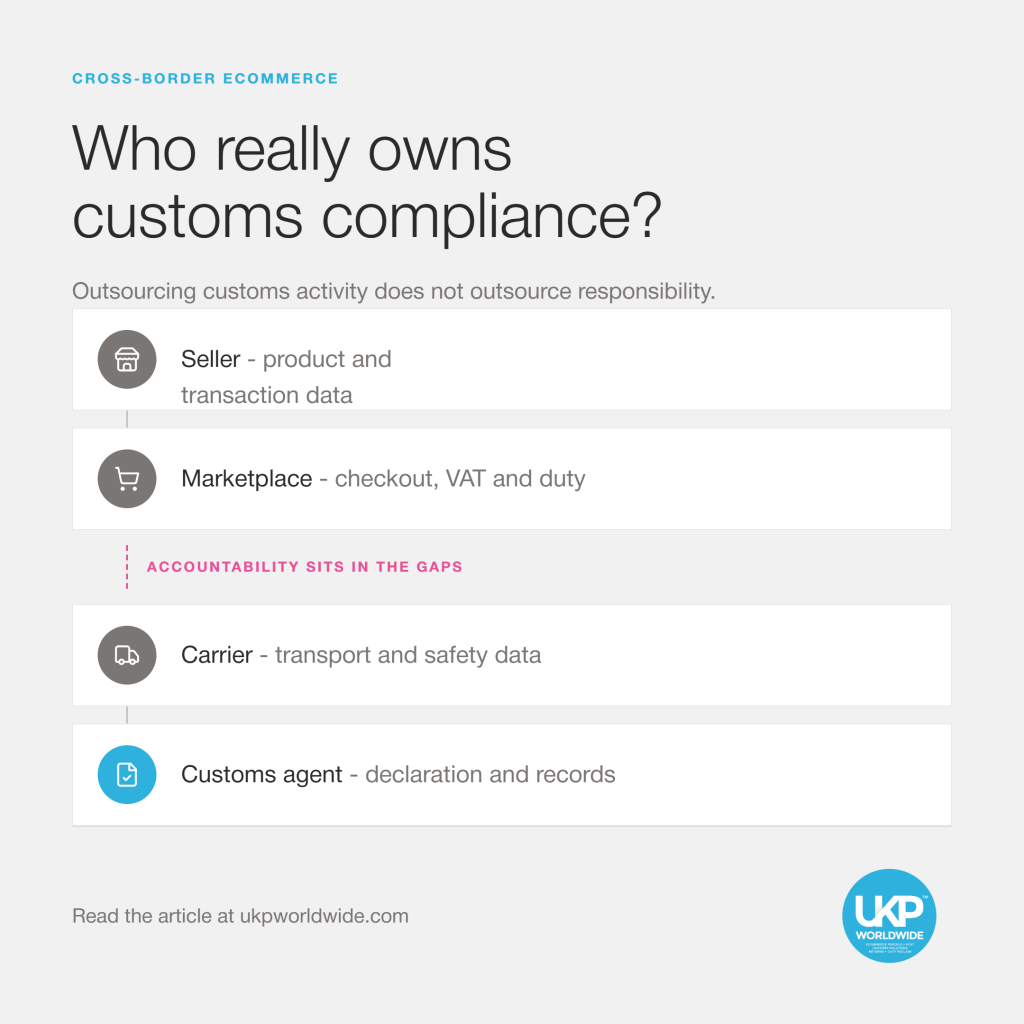
Who really owns customs compliance?

This article is for retailers, online marketplaces, fulfilment providers, carriers and logistics partners involved in moving eCommerce goods across international borders. It explains why customs compliance cannot be treated as the responsibility of one supplier alone, where accountability can become unclear and what businesses should establish before goods begin moving.

With UK and EU reforms placing greater responsibilities on sellers and online platforms, understanding who creates, checks and submits customs information is becoming increasingly important.

Outsourcing customs activity does not outsource responsibility.

An international eCommerce order may pass through a retailer, marketplace, fulfilment provider, carrier, customs agent and final-mile delivery partner before it reaches the customer.

Each business performs a different part of the process. But when the product description is unclear, the commodity code is incorrect, or the customs value does not match the transaction, who is responsible? The answer is not simply the business that submitted the customs declaration.

Customs compliance is a shared process, but responsibility for the underlying information must still be clearly assigned. A customs agent can prepare and submit a declaration, identify inconsistencies and advise on customs requirements. It cannot, however, manufacture accurate product information that does not exist or correct commercial data that was wrong at source.

This distinction is becoming increasingly important as customs authorities expect more detailed information earlier in the transaction and governments move responsibilities closer to overseas sellers and online marketplaces.

Customs compliance begins with the data owner.

The information needed for customs clearance is created long before a parcel reaches the border. The seller is usually best placed to know what the product is, what it is made from, where it was manufactured and how much it was sold for. A marketplace may control the product listing, customer payment and collection of taxes or duties. The fulfilment provider knows what was packed, while the carrier holds the transport information.

The customs agent brings these different pieces of information together to complete the customs process. The quality of the declaration therefore depends on the quality of the data received from across the supply chain.

If a seller provides a vague description such as “clothing”, “accessory” or “gift”, other parties may not have enough information to determine the correct classification. If the declared value does not reflect the transaction, a carrier or agent may have no independent way to identify the correct amount. If the country of origin has been assumed rather than properly established, the wrong duty may be applied. This is why customs compliance cannot begin at the point of declaration. It must begin with the creation and management of product data.

Online marketplaces are becoming increasingly important within this process. Under the EU Import One Stop Shop, or IOSS, suppliers and qualifying electronic interfaces can collect VAT at the point of sale for imported consignments not exceeding €150. In certain circumstances, a marketplace can be treated as the deemed supplier for VAT purposes.

However, IOSS is a VAT simplification. It does not remove the need for a valid customs declaration or accurate customs data. The party collecting VAT, the importer, the customs declarant, and the business supplying the product information may still be different organisations. European Commission guidance on low-value consignments.

The direction of travel is towards greater marketplace involvement. The European Commission’s proposed customs reforms would make online platforms key participants in ensuring that duties and VAT are paid at purchase. European Commission overview of EU customs reform.

The UK is moving in a similar direction. Under proposed reforms to the customs treatment of low-value imports, overseas sellers and online marketplaces would be responsible for collecting customs duty and accounting for it through a new system. The arrangements are expected to take effect by October 2028 at the latest. UK Government response on low-value import reform.

These developments reinforce a wider point: customs responsibilities are moving closer to the product listing, checkout and point of sale. Retailers and marketplaces will need to treat customs data as a core part of the eCommerce transaction, rather than information assembled only when the parcel is ready to leave.

Outsourcing the declaration is not the same as transferring responsibility

Appointing a customs agent is an important way for businesses to access specialist knowledge and manage complex customs processes. It does not mean the trader can step away from the accuracy of the information being declared.

In the UK, an agent can act as either a direct or indirect representative:

Under direct representation, the agent submits the declaration in the trader’s name and on its behalf. The trader remains responsible for the customs debt and the accuracy of the underlying information.

Under indirect representation, the agent acts in its own name but on behalf of the trader. The agent and the principal may then be jointly and severally liable for the customs debt. HMRC can seek payment from either party. HMRC guidance on customs debt liability.

The type of representation therefore matters, but neither arrangement removes the need for accurate information from the business that understands the products and transactions.

Customs agents have responsibilities of their own. They must understand the authority under which they are acting, maintain appropriate records, conduct reasonable due diligence and question information that appears inconsistent or implausible.

A strong customs relationship is therefore a partnership. The retailer or marketplace provides accurate, complete and properly governed data. The customs agent applies specialist knowledge, challenges potential errors and ensures the information is used within the correct customs process.

Carriers and logistics providers also have defined responsibilities. For example, the carrier moving goods into Great Britain is responsible for ensuring that an Entry Summary Declaration is submitted. A third party may lodge it on the carrier’s behalf, but the carrier remains responsible for making sure the submission takes place. HMRC guidance on Entry Summary Declarations.

This demonstrates the difference between performing an activity and owning responsibility for it. A task may be delegated to another business, but the legal or operational obligation may remain with the original party.

Responsibility must be agreed before the parcel moves

The greatest compliance risks often appear in the gaps between businesses. A marketplace may assume the seller has validated the commodity code. The seller may expect the carrier to classify the goods. The carrier may assume it will receive declaration-ready information from the fulfilment provider. The customs agent may receive only the limited data transmitted through the shipping label.

Everyone has performed their part, but no one has taken ownership of the whole data journey. By the time the problem is identified, the parcel may already be moving. The result can be an incorrect duty calculation, delayed clearance, unexpected customer charges, a rejected declaration or a retrospective customs debt. When the same weakness is repeated across thousands of consignments, a small data problem can become a significant commercial and compliance risk.

For every international sales route, businesses should be able to answer:

  • Who determines and approves the commodity code?
  • Who confirms the customs value?
  • Who establishes and evidences the country of origin?
  • Who will act as importer?
  • Who calculates and collects duties and taxes?
  • Who supplies the customs and safety and security data?
  • Is the customs agent acting directly or indirectly?
  • Who investigates and corrects inaccurate information?
  • Who retains the supporting evidence and audit trail?

If these questions cannot be answered clearly, the compliance model is not clear enough.

Contracts can help define the responsibilities of each party, but contractual wording alone will not make customs data accurate. Responsibilities must also be reflected in operational processes, system integrations, data checks and exception management.

The question businesses should ask is not simply, “Who submitted the declaration?” It is, “Who created the information, who checked it and who was expected to act if something did not look right?”

Customs compliance can be shared across several businesses. It cannot be left to assumption.

As responsibility moves closer to the point of sale, the businesses best prepared for future reforms will be those that define ownership early, maintain reliable product data and involve their customs partners before goods begin moving.

Outsourcing customs activity can provide valuable expertise and operational support. What it cannot do is outsource responsibility for getting the underlying information right.